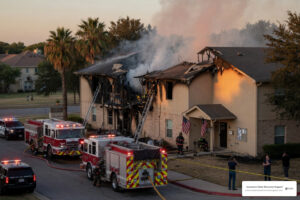
In 2023, our family woke up to a nightmare. Our house was filled with smoke and on fire. We able to get our son and pets out of the burning house without injury, and our local fire department arrived quickly and put out the fire. By the time that the fire was out, most of our home was destroyed. We contacted our insurer to start a claim and were immediately met with opposition and confusion on their part. It took several weeks for them to assign an adjuster to our claim. This initial experience led our decision to hire a Public Adjuster to navigate the process and advocate on our behalf. We couldn’t trust that our insurer would handle the claim responsibly, and we quickly realized that we needed someone to fight for us to hold them accountable to our policy. We were extremely fortunate to find ICRS and secure Scott as our Public Adjuster.
Our Insurer mislead us and withheld information. It took weeks for them to provide a copy of our policy, and when they did, they excluded information that benefited us. ICRS pressured them to provide a full copy of our policy which included the benefits they had initially excluded.
Our Insurer provided a scope that was not aligned with the actual cost of rebuilding our home. ICRS countered with a realistic scope and advised us to secure independent quotes on our own. ICRS then leveraged its scope and the independent quotes to force our insurer to provide more realistic amount for the rebuild. The scoping process took months, and ICRS drove the communications the entire time.
The first adjuster that our insurer assigned to our claim arrived at the site visit and interview with a combative attitude, where he used inappropriate language, and attempted to force the negotiations their favor by manipulating the facts. ICRS swiftly called out the adjuster and guided the negations back on track.
Our Insurer cycled through four adjusters during our claim. The pass-down of information between these adjusters was insufficient, with each new adjuster attempting to avoid payout using the same methods that failed with the last. We were astonished that a company could act in this manner without serious recourse. ICRS was able to leverage emails, photos, inspection reports, and additional documentation to bring the adjusters up to speed after each transition. ICRS’ efforts kept the claim moving every time our insurer attempted to stall.
When our Insurer misrepresented the policy and refused to pay out for damages that were covered, ICRS drove the communications process and provided documentation, which included case-law excerpts from similar claims that had gone to trial. This approach provided breakthroughs on vital areas of the negotiations. ICRS provided a paper trail and documentation that our Insurer couldn’t ignore, and ultimately they were forced to pay out due to the exposure that ICRS had made apparent.
ICRS increased the overall claim by more than 20% during the planning and rebuild process through supplements. Through negotiations with our Insurance company, ICRS increased the claim by 104% over what was released up-front in our initial settlement. Additionally, the payout ICRS secured for us was 31% higher than our policy limit.
Before that fire, we had heard insurance companies pull out every trick in the book to avoid paying out on a policy. Having gone through this experience, we can say that the behavior on our insurers part was far worse than we had ever imagined possible. We advise with 100% conviction that anyone dealing with a large loss such as ours, hire a public adjuster to navigate and advocate on their behalf in order to get the needed results. Our family could not have rebuilt our home with the funds our insurance company provided, and we only have a home to return to because of ICRS’ efforts to hold our insurer accountable for the policy we had paid for. Throughout the claim, which lasted over a year, ICRS navigated the entire claim process with professionalism and care. Our family offers a sincere thank you to Scott, Misty, and the entire ICRS team.